A rewards credit card (“rewards card”) gives you something back on the spending you already do, usually as points, cashback or dollars you can use later.
Whether you already have a rewards card or you’re weighing one up, this guide covers what makes a rewards card worth it and what to look for when you compare them.
We use NOW Rewards Visa as the example, but the thinking applies generally to credit cards with a rewards programme.
In this article:
- How do rewards credit cards work in New Zealand?
- What should you look for in a rewards card?
- Can a rewards card also offer interest free finance?
- How do the NOW Rewards Visa NOW Dollars work?
- How much could I earn in a year?
- What else should I know about the NOW Rewards Visa?
- Frequently asked questions
How do rewards credit cards work in New Zealand?
A rewards card earns you something back on everyday spending, but it only comes out ahead if the card does not cost you more than it gives. Three things decide that:
- Pay the balance in full each month. Purchase interest rates sit above any rewards rate, so even a little interest carried month to month outweighs what you earn in rewards. Rewards favour people who clear the card each month.
- Put spending you would do anyway on the card. Groceries, petrol, the power bill. The rewards add up because that spending was always going to happen, not because you spent more to chase them.
- Weigh the rewards against the fee. A rewards card usually has an account fee, or annual fee, so the real question is whether what you get back, plus the other things the card does, is worth that flat cost.
Rewards cards have shifted in New Zealand lately. It is worth checking what a card still offers before you choose.
What should you look for in a rewards card?
Comparing rewards cards comes down to a few practical questions:
- What you earn, and what it is worth. Check the earn rate and what a point or dollar is worth when you use it. One point does not always equal one dollar.
- Where you can use the rewards. Some rewards work like cash at a set list of retailers. Others are points in a scheme you redeem for things like flights, products or experiences.
- The fee against the value. Work out what you would realistically earn back in a year and weigh it against the account fee. If you spend a little, a lower fee matters more than a high earn rate.
- What else the card does. A card is more than its rewards. Things like long-term interest free finance, fraud protection and a digital wallet can be worth more than a slightly higher earn rate.
Can a rewards card also offer interest free finance?
Rewards are one thing a card can give you. Long-term interest free finance is another. Not every card offers both.
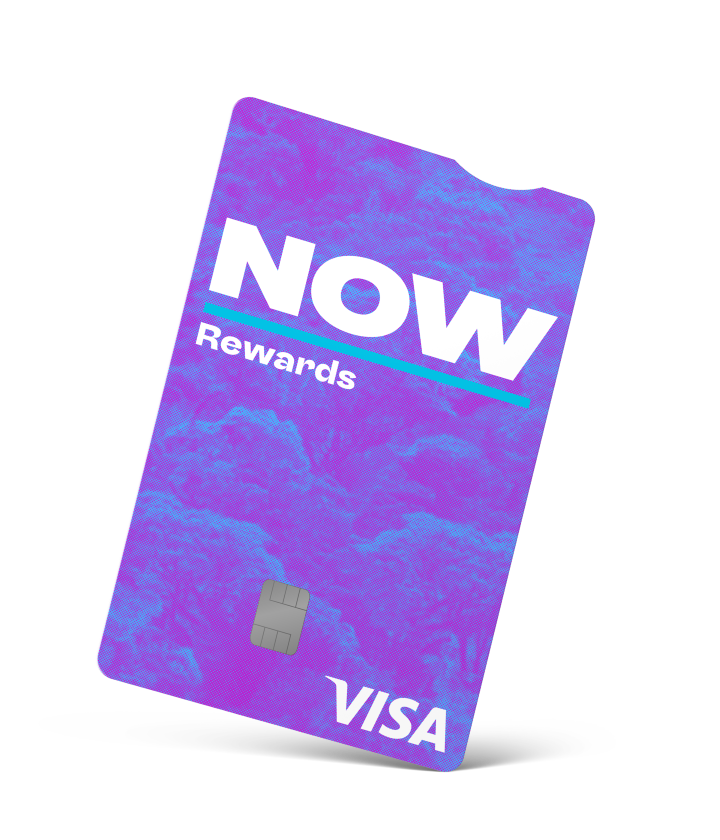
That combination is the idea behind NOW Rewards Visa. You earn NOW Dollars on eligible everyday Visa spend, and at participating retailers you can spread a larger purchase over a long-term interest free plan. There is also automatic 12 months interest free on single purchases of $250 or more at Noel Leeming, The Warehouse and Warehouse Stationery, with nothing extra to set up.
So, the same card that chips away at the weekly shop can also turn a new fridge or a set of tyres into predictable payments, which matters more when budgets are tight.
For how these plans work, see our guide to how interest free finance works, and for weighing up a bigger buy, our guide to paying for a big purchase.
How do NOW Rewards Visa NOW Dollars work?
You earn 1 NOW Dollar for every $150 you spend on eligible purchases, and 1 NOW Dollar is worth NZ$1 to spend at redemption partners. You earn anywhere Visa is accepted, in store or online, including bills you put on the card such as power, water, broadband, mobile and rates. A few things do not earn:
| Earn NOW Dollars | Doesn’t earn NOW Dollars |
|---|---|
| Everyday Visa spending (groceries, petrol, online) | Cash advances and balance transfers |
| Power, water, broadband, mobile and rates | Long-term interest free plans you apply for |
| Most other everyday Visa purchases | Fees, interest, NOW Dollars redemption |
When you shop at a participating retailer, you (the main cardholder) will get a text offering to put your NOW Dollars towards that purchase. A minimum spend applies, and saying yes uses your whole balance at once, so it is worth saving them for something you really want.
You can let your NOW Dollars build up rather than spending them straight away. That makes them handy for saving towards a bigger spend, like Christmas presents or back-to-school costs. Both the main cardholder and any additional cardholder earn, and all the NOW Dollars sit in the main cardholder’s account.
You can see the full detail of how to use the rewards and where you can redeem on the NOW Rewards Visa page.
How much could I earn in a year?
Say a household puts about $3,000 a month of everyday spending and bills through the card. Over a year that builds up like this. (This is an illustration; your own depends on what you spend.)
| Over a year | Amount |
|---|---|
| Eligible spend on the card ($3,000 a month) | $36,000 |
| NOW Dollars earned | 240 |
| What they’re worth at certain participating retailers | $240 |
The maths is simple: every $150 of eligible spend earns 1 NOW Dollar, so divide your yearly card spend by 150. Long-term interest free finance you apply for does not earn, so it is not counted here.
What else should I know about NOW Rewards Visa?
- Clearing the balance is what makes rewards cards pay off. Like any credit card, the NOW Rewards Visa charges interest on a balance you carry (see our rates and fees), and that adds up faster than NOW Dollars you earn. Pay it off in full each month and you'll get the full benefit of the rewards you earn.
- The two kinds of interest free work differently. On a single purchase of $250 or more at Noel Leeming, The Warehouse or Warehouse Stationery, the automatic 12 months interest free still earns NOW Dollars. Purchases on long-term interest free with merchants other than the three above, or on terms longer than 12 months with those merchants, will be held as a separate balance and won't earn NOW Dollars
- Only the main cardholder redeems. Additional cardholders earn NOW Dollars too, but they go to the main cardholder’s account, and the redemption text goes to the main cardholder.
Frequently asked questions
There isn’t one best card for everyone. The best rewards card for you is the one whose rewards match what you already spend on, whose account fee is worth what you get back, and whose extras you will use. Work through the points above, then compare a couple of cards on those terms.
Yes. The NOW Rewards Visa earns NOW Dollars on everyday Visa spend, and at participating retailers you can spread a larger purchase over a long-term interest free plan.
It depends. On a single eligible purchase of $250 or more at Noel Leeming, The Warehouse or Warehouse Stationery, the automatic 12 months interest free purchase will earn NOW Dollars. Long-term interest free plans you apply for at a retailer do not.
They do not currently expire, so you can save them up for something bigger.
New to credit cards, or weighing up which one suits? See our guide to choosing a credit card in NZ in 2026. And for keeping your card and payments safe, see our guide to paying safely by credit, debit or EFTPOS.
The information on this website is provided for general information only. Finance Now does not assume any responsibility for giving legal or other professional advice and disclaims any liability arising from the use of the information. If you require legal or other expert advice you should seek assistance from a professional adviser.
About Finance Now
Finance Now is a 100% Kiwi-owned consumer lender, trusted by more than 530,000 New Zealanders. If the NOW Rewards Visa sounds like it might suit, you can find the full rates, fees and how to apply on our product pages. NOW Rewards Visa is issued by SBS Money Limited, which is wholly owned by Finance Now Limited.
Share this article